FinCEN and the Fed withdraw a 2020 plan to lower the travel rule threshold to $250
The agencies said five years had passed and the crypto market had changed, and promised a new comment period before any similar rule.
The Financial Crimes Enforcement Network (FinCEN) and the Federal Reserve Board announced on November 6 that they are withdrawing a proposed rule that would have lowered the threshold for record-keeping on cross-border funds transfers and clarified that the rules cover transactions in convertible virtual currencies such as Bitcoin. The withdrawal took effect when it was published in the Federal Register on November 9.
What was withdrawn
The proposal would have "amended the Recordkeeping and Travel Rule regarding convertible virtual currencies" and lowered the threshold "for funds transfers and transmittals of funds that begin or end outside the United States," FinCEN said. It is "jointly withdrawn with the Federal Reserve Board of Governors."
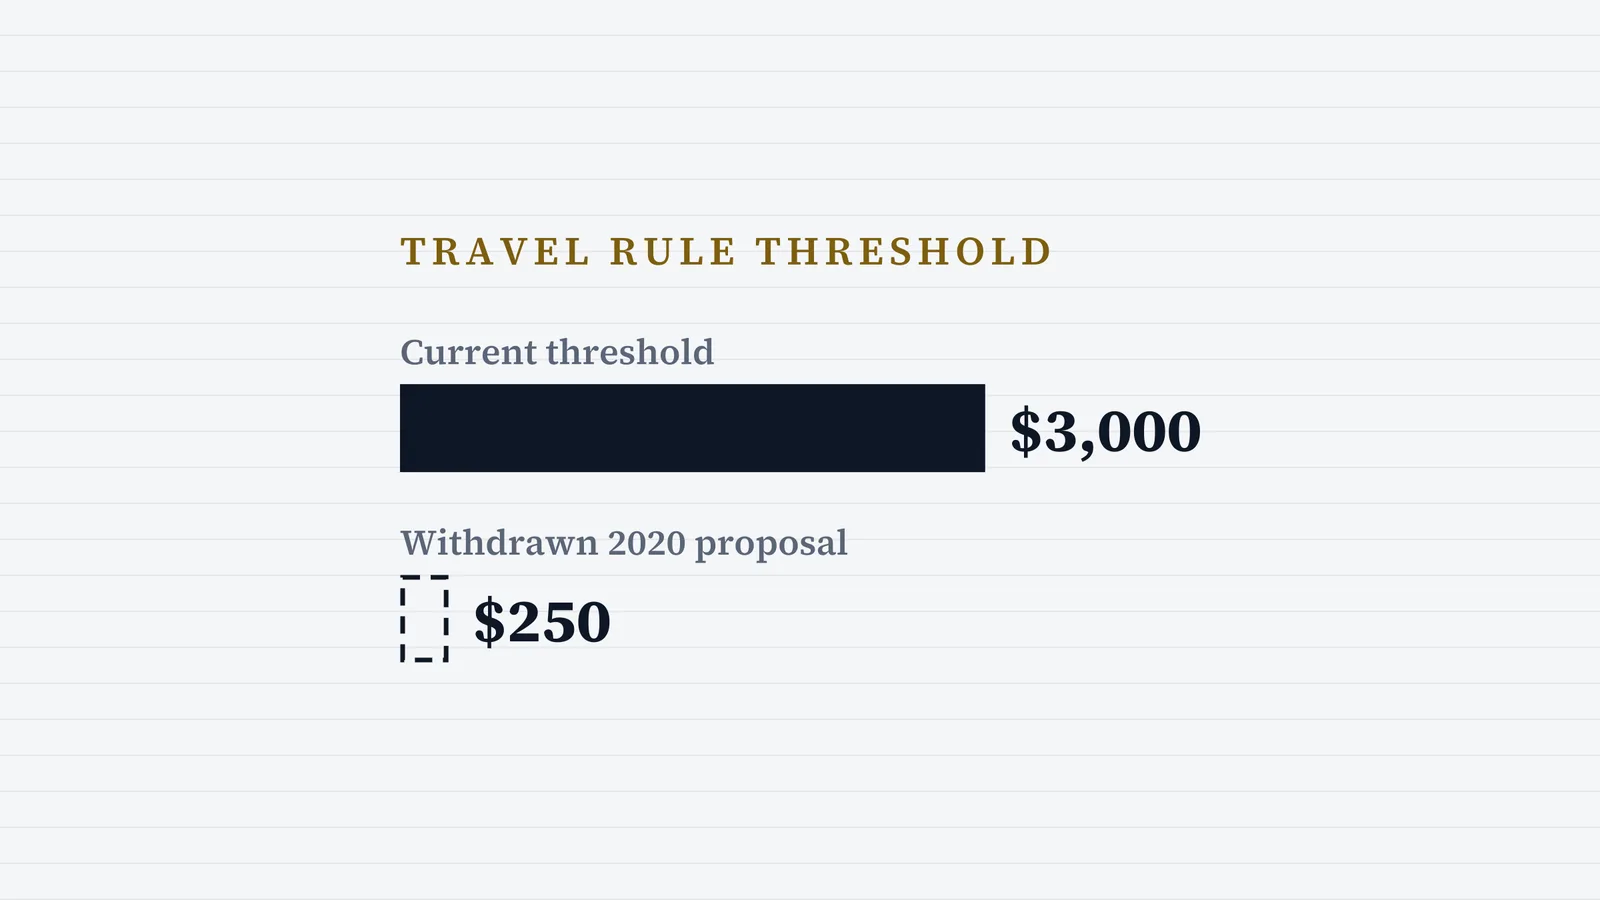
When the agencies first proposed the change in October 2020, they planned to cut the threshold from $3,000 to $250, the ABA Banking Journal reported at the time. They argued then that law enforcement would benefit from data on more transfers and that the effect on the financial system would be low.
The Federal Register notice gives two main reasons. More than five years have passed since the proposal, and the agencies want more public feedback before adopting any similar change; withdrawing it means no final rule can be issued without a new chance to comment. The crypto industry has also changed significantly since 2020, with new legal frameworks such as the GENIUS Act, and the agencies said any future amendments involving convertible virtual currencies should take those developments into account. The agencies received nearly 3,000 comments on the 2020 proposal, and commenters generally opposed the lower threshold, the notice said.
Why it matters
A $250 threshold would have pulled far more small international transfers, including crypto transfers handled by regulated firms, into record-keeping requirements. Withdrawing it leaves the current threshold in place for now. The agencies left the door open to a new proposal, which would again be subject to public comment. The decision came on the same day FinCEN ordered US financial institutions to cut off the crypto exchange MEXC once that order takes effect.
What it could mean for traders
For users of regulated US platforms, little changes day to day: existing record-keeping rules continue to apply. For firms that move small cross-border transfers, the withdrawal removes the 2020 plan, but not the possibility of a new one.
Sources
- FinCEN and Federal Reserve Board (Federal Register) — Threshold for the Requirement to Collect, Retain, and Transmit Information on Funds Transfers and Transmittals of Funds; Withdrawal (FR Doc. 2026-22809) (November 9, 2026)
- FinCEN — FinCEN Announces Withdrawal of Proposed Rule Related to Recordkeeping and Travel Rule Obligations (November 6, 2026)
- ABA Banking Journal — Fed, FinCEN propose to lower reporting threshold for funds transfers (October 23, 2020)
This article was researched and drafted with the help of AI tools, checked against its sources in a separate AI fact-check and edit, and approved for publication by Trading Metrics. Read our AI use policy.
This article is for information only and is not financial advice. Crypto assets and leveraged products are volatile and you can lose money. Do your own research and consider your circumstances before trading.